Irish Co-Founded Imprint Takes Top Spot on Deloitte's 2026 Fast 500
Irish co-founded fintech Imprint tops Deloitte's 2026 US-Canada Technology Fast 500 and recently raised $130m at a $1.9bn valuation.
Imprint has ranked first on Deloitte's 2026 Technology Fast 500 for the US and Canada, and the timing is hard to miss. The New York-based fintech raised $130m in new financing the week before the ranking was published, valuing the company at approximately $1.9bn. For a business that started in 2020, that's a fast run by any measure.

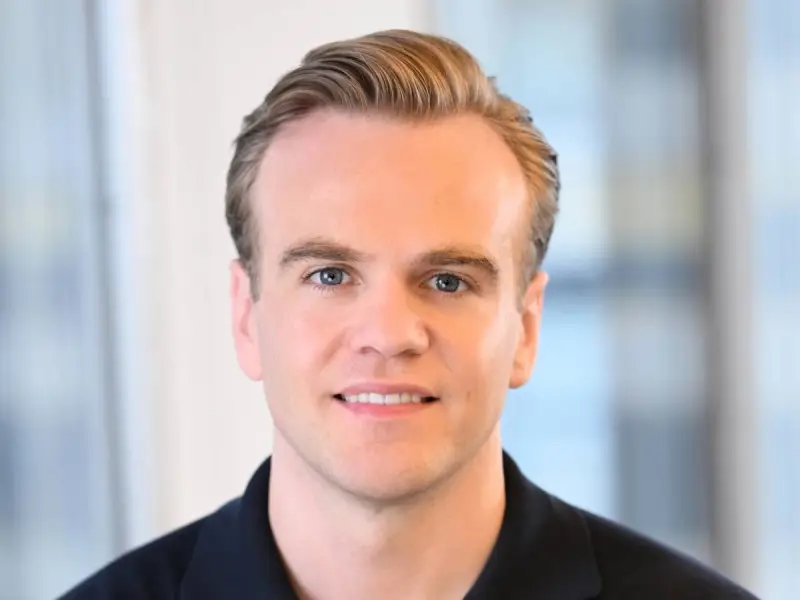
CEO and co-founder Daragh Murphy. Image: Imprint
What the ranking measured
Deloitte's Fast 500 is a growth league table rather than a size ranking. It favours companies that have expanded quickly over a set period, so a young firm can outrank much larger incumbents. Imprint's position reflects that. It took the top spot with a growth rate of 66,330% between 2022 and 2025, as given in the ranking. Biotech company ImmunityBio came second and digital healthcare platform Finni Health came third.
Read the number with some care. Percentage growth figures in these lists are very sensitive to the starting base. A company that grew from a small early revenue figure can post a headline percentage that looks extraordinary, even when its absolute scale is still modest. That doesn't diminish the result, but it's the kind of detail worth checking if you're using these rankings in a vendor shortlist or a board paper.
Who founded it and where it came from
Imprint was co-founded in 2020 by Irishman Daragh Murphy and Gaurav Ahuja. Murphy studied law at University College Dublin and was previously vice-president of operations and strategy at workspace provider WeWork. He is now CEO of Imprint. The Irish link is the angle Irish press has picked up, but the company itself is headquartered in New York and sells mainly into the US market.
In December, Imprint reached unicorn status after a $150m Series D round that put its valuation at $1.2bn. The latest $130m round, which values the business at roughly $1.9bn, shows the valuation has moved up quickly in a short space of time.
What Imprint actually sells
Imprint works with brands to design, launch and manage co-branded custom credit card programmes. It also helps companies learn from customer interactions so they can deliver personalised recognition and rewards. In practical terms, a retailer or consumer brand can offer its own branded card, with rewards tuned to its customers, without building the card infrastructure itself.
The company says it serves more than 2m members and partners, including Shell, Booking.com and Rakuten. It also says the brands it works with represent more than $500bn in annual US consumer spending. Those are Imprint's own figures, and they haven't been independently verified in the material available here, so treat them as the company's claims.
The model sits in a part of fintech that has been drawing steady attention. Co-branded cards and loyalty schemes let brands keep customers returning, and the card provider gets a route into consumer spending data and fee income. Whether a given brand sees that as worth the operational work depends on its customer base and margins, and that's a judgement each business has to make for itself.
Where the money is going
The $130m round was led by existing investor Khosla Ventures. Existing investors Hedosophia, Ribbit Capital, Spice and Thrive Capital took part, and Positive Sum came in as a new investor. Imprint says it will use the funding to expand into new payment options and to build AI capabilities "that help brands recognise and reward customers wherever and however they choose to pay".
That AI reference is worth a closer look. Murphy framed it around how shopping is changing. In his words: "Our mission is to make every customer a regular. As AI changes how people shop, we're helping the most beloved brands turn everyday payments into stronger relationships." He also said topping the Fast 500 "reflects the strength of our team, the demand for what we're building, and the opportunity ahead of us."
Imprint's stated three-year goal is to become "the platform that powers premium access for the customers of leading brands". That's a broad ambition, and it's one to watch. Companies that set out to be a platform often end up adding services well beyond their original product, and each addition brings its own integration and risk questions.
What this means for IT and procurement teams
Most readers here won't be choosing a co-branded card provider next week. But the pattern matters for anyone who supports customer-facing payments, loyalty data or marketing platforms. Here's my read on what to take from it.
First, if your organisation is looking at outsourcing card programmes or rewards to a fast-growing fintech, the growth ranking tells you about momentum, not about operational maturity. Ask about data handling, integration options with your existing CRM and payment stack, and how the provider manages change when it adds new payment methods. Those answers will matter more than a headline growth figure once the contract is live.
Second, rapid funding and valuation increases usually come with pressure to expand the product set quickly. That can mean more integrations, more data flows and more third-party connections to review. Teams in this position typically find that their vendor risk reviews need to be repeated more often than the contract cycle suggests, because the product they bought in year one may not be the product running in year three.
Third, the AI capabilities mentioned in the funding announcement are described only in general terms in the material available. If an AI feature is going to touch customer or payment data in your environment, get the specifics in writing before it's switched on. Don't assume the feature set you were pitched is the one you'll get.
What to watch next
The main things to track are whether Imprint's new payment options arrive on the timeline it sets, how it describes the AI capabilities once they're live, and whether its partner list grows beyond the names it has already given. Growth rankings are a snapshot of a single period, and the next Fast 500 will show whether Imprint sustains that pace or levels off.
For now, the story is a clear one: an Irish co-founded company has topped a major North American growth list, raised a large round at a much higher valuation than a year earlier, and is pushing into AI-driven payments. It's worth knowing about, and worth checking carefully before it shows up in your own vendor pipeline.


